Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 221

Goldilocks economy is keeping bears at bay

Pick up a newspaper today and it is hard to find many reasons to be cheery. North Korea and ISIS take turns in frightening us for our lives. Brexit and Trump take turns in frightening us for our livelihoods. Most financial commentators are fixated on predicting how soon it will be until the next bear market hits shares.

Recognise the synchronised upswing

It is unfortunate then, that one of the better good news stories of recent years has received less attention than it deserves. Since mid-2016, a string of consistently good economic data from around the world has shown the global economy is in a period of synchronised upswing. In the US, economic growth annualised at a rate of 3.1% in the second quarter of this year, well ahead of market expectations, while Europe and Japan both recorded annualised growth rates of 2.5% during the same period. For mature developed market economies, such growth rates are positively zippy.

An equally important driver of above-trend global growth has been developments in China. Not that Chinese growth rates have been accelerating, but rather Chinese growth has (once again) not slowed down as forecast. The Chinese economy grew by 6.9% in the second quarter of 2017, the same rate of growth as the first quarter and the equal fastest pace of expansion since September 2015. Chinese growth rates are considerably ahead of its government’s own 2017 growth forecast of ‘around 6.5%’. A year ago, markets (and the Chinese government) were predicting a meaningful slowdown during 2017 as the government tackled excess credit creation and forced closures in industries with excess capacity. So far, predictions that these actions would weigh heavily on economic activity have proven to be incorrect, or at least premature.

The IMF, in its most recent review of the global economic outlook, forecasts the global economy to expand by 3.5% in 2017 and 3.6% in 2018. This would represent the fastest pace for global growth since 2014 and 2011 respectively. It would also seem that there is room for meaningful upside to the IMF’s 2018 figures; as they are predicated on Chinese growth falling to 6.2%, a significant slowdown from the current rate of activity.

Where’s the inflation and unemployment?

What is remarkable about this upswing in global economic activity is that it is occurring at a time of both benign inflation and, on some measures, close to record low unemployment. The OECD average unemployment rate fell to 5.6% during June 2017, its lowest level since March 2008 (see chart below).
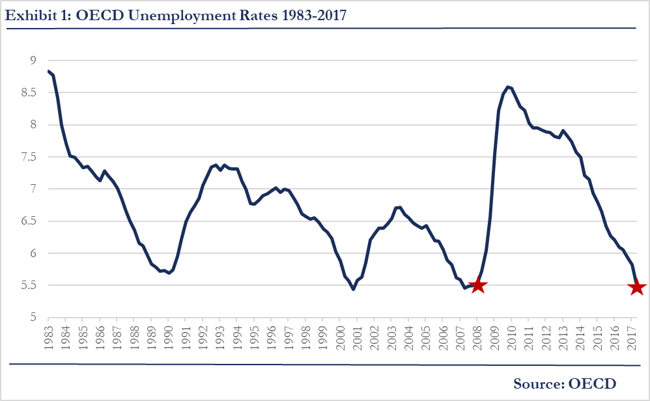
However, considerable spare capacity remains in the labour force. Workforce participation levels have fallen substantially in key economies like the US, with large swathes of potential workers falling out of the labour market following years of difficult economic conditions. This dynamic means that, despite the low headline unemployment rates, wage growth in developed market economies remains anaemic. The accelerating global economy is pulling workers back into the labour market instead of giving the existing workforce a pay rise. This lack of labour market pricing power is one of the key contributors to inflation remaining too low for most major economies. The three most important central banks, the Fed, ECB and BOJ, are all engaged in unprecedented monetary easing programs designed in large part to push inflation rates higher.

Strength feeding profitability

A combination of accelerating global growth, benign inflation and ultra-easy monetary conditions (real interest rates in the US, the Euro area and Japan all remain negative) has created a Goldilocks environment for equity markets. Corporate profitability is the chief beneficiary of accelerating growth in an environment of negative real interest rates and limited wage pressure.

Yet despite the positive economic backdrop, much of the commentary about equity markets today is anchored around one key worry – how long it has been since the last big correction, nearly a decade since the last. It is also true that share markets do not turn on some preordained cycle. They price in the market’s best estimate of future corporate earnings. In large part, the reason that share markets continue to make new highs today is that the global economy is in unusually rude health, and that, for now, corporate profitability stands to be the biggest beneficiary from this upswing.

While this is good news for investors, it is better news for large parts of the population removed from the workforce following years of sub-par economic growth. ‘Falling labour market slack’ is an economist’s way of saying that, nine years on from the crisis, many marginalised members of society are finally able to find work. Surely one of the better news stories of recent years.


Miles Staude is Portfolio Manager at the Global Value Fund (ASX:GVF), which he manages from London. This article is the opinion of the writer and does not consider the circumstances of any individual. The title of this piece apes a famous economic article written in 1992 by David Shulman, a senior economist at UCLA.


  •   4 October 2017
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Checking in on the equity market's silent engine

Bear markets don't go paw-in-paw with recessions

Suddenly, the market cares if a company makes money (again)

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.