Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 430

Slowing global trade not the threat investors fear

Contributing authors: Jonathan Lemco, Asawari Sathe, Adam J. Schickling, Maximilian Wieland, and Beatrice Yeo, from the Vanguard Investment Strategy Group’s Global Economics Team.

The last 12-plus months have emphasised that the COVID-19 pandemic would accelerate trends already in place. One of these trends is the shortening, and in some cases the reshoring, of supply chains, as business leaders question whether their supply chains have been stretched too far and become too complex.

Such a trend raises a natural question: Is globalisation dead?

New Vanguard research, The deglobalisation myth(s), concludes that, no, globalisation isn’t dead. Instead, global trade growth is likely to slow, as it’s been doing since the GFC. This slowing in global trade growth, what we term ‘slowbalisation’, is unlikely to turn into a contraction in global trade. What’s more, the implications for investors are only modest.

A slowbalization scenario is the most likely outcome
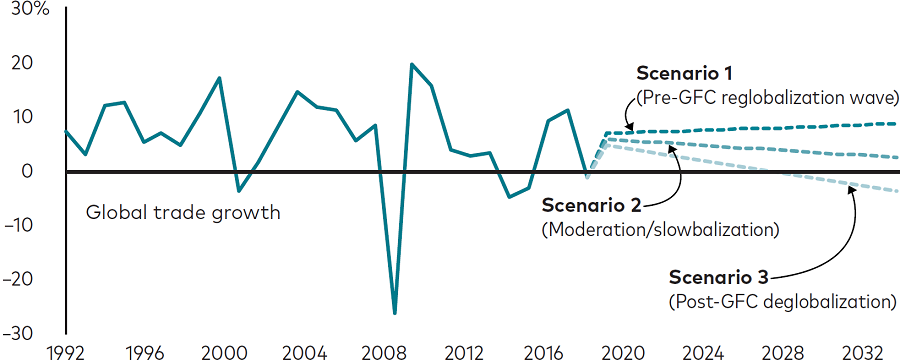
Sources: Vanguard calculations, using data from the World Bank, the Organisation for Economic Co-operation and Development, and the KOF Swiss Economic Institute.

The allure of global trade is understandable

Companies that produce goods or provide services want the largest possible markets for their outputs. But a structural expansion in supply chains, which boosted gross trade in the 1990s and early 2000s, started to slow even before the GFC. A turn toward protectionism - government policies that favour domestic industries - over the last decade in the face of rising inequality in developed economies is likely to similarly tap the brakes on global trade.

We note that other aspects of globalisation, including international capital flows, knowledge sharing, and geopolitics, carry potentially significant economic, societal, and environmental consequences. Our latest research focuses on just one aspect of globalisation that addresses a specific concern of investors: the trade of goods and services.

The concern is that slowing global trade growth may reduce corporate earnings and profit growth and, by extension, weigh on equity prices. After all, a globalisation wave that began in the 1990s coincided with a six-fold increase in S&P500 Index earnings per share and more than a doubling of profit margins, contributing to almost 90% of the index’s price return over most of three decades.1

Risks to investors may not be as great as they seem

But we contest the view that globalisation has been the central factor in the expansion of these return drivers. Our research demonstrates an inconclusive or weak relationship between earnings growth and changes in trade dependency. And it shows that industries with the greatest increase in profit margins since 1990 - finance and insurance, and office and computer machinery are examples - have experienced only modest changes in trade dependency.

Trade tensions that precipitated sharp bouts of market volatility just a few years ago underscore the importance that investors ascribe to global commerce with few impediments. No doubt, geopolitical risks are ever present and worthy of attention. But our new research quantifies risks related specifically to a future of slowing global trade growth, and we believe that these risks to investors aren’t as large as they’re sometimes portrayed.

Rather, we emphasise conclusions shared by our new research and our December 2020 research A Tale of Two Decades for U.S. and Non-U.S. Equity: that corporate earnings growth hasn’t been a major contributor to U.S. equity outperformance in the past and that we shouldn’t expect it to have a meaningful impact on future outperformance or underperformance.

Valuations, or the price investors pay for earnings, represent the most important signal for future asset returns.


1 The average annual S&P 500 Index price return from 1990 to 2018 was 7.4%. Three factors make up this return: valuation expansion/contraction (dollar paid per dollar of earnings), earnings growth from revenue growth, and earnings growth from ratio of earnings to revenue (profit margins). Contributions from these factors were 0.8%, 3.7%, and 2.9%, respectively. 


Vanguard is a sponsor of Firstlinks. This article is for general information and does not consider the circumstances of any individual. For more articles and papers from Vanguard, please click here.


  •   20 October 2021
  • 1
  •      
  •   

RELATED ARTICLES

The folly of the Iran war

Europe: A new growth trajectory powered by reform and investment

REITs: a haven in a Trumpian world?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.