Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 77

Policy pincers in Australia and the US

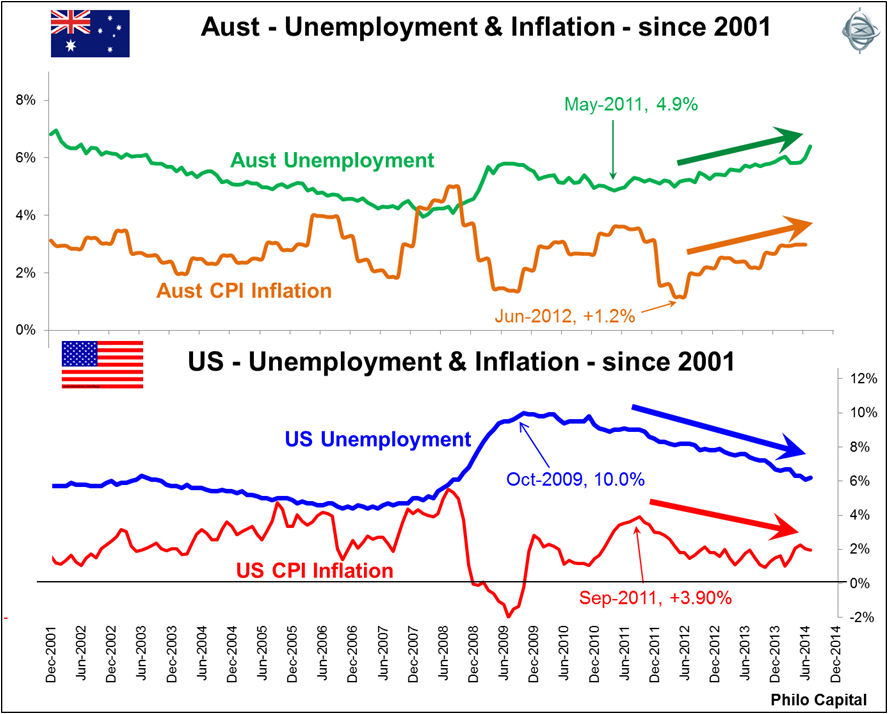
In the US, the two big policy imperatives – unemployment and inflation – have been going in the right direction (down) since 2011. Ultra-loose fiscal policy (four years of trillion dollar budget deficits) and ultra-loose monetary policy (near- zero interest rates and unprecedented money printing) have borne fruit, albeit slowly:- the economy is growing, the unemployment rate is falling, the budget deficit is contracting, deflation has been avoided, inflation has been low, and asset prices are rising (including shares, bonds, housing and commercial property). The ‘QE’ money printing program is coming to an end without rattling asset markets or investor confidence.

Falling unemployment plus very low inflation, despite the strong dollar and tightening budget, mean the Fed can start tightening monetary policy by raising interest rates. The big risk is that the Fed continues to dismiss rising inflation as ‘noise’, and keeps interest rates too low for too long. The likely outcome is that the Fed will wait too long and have to hit hard with unexpected interest rate hikes, rattling investment markets, as in 1994.

Standing behind Fed Chair Janet Yellen now is the new Fed Vice Chairman Stan Fischer who, as head of Israel’s central bank from 2005 to 2013, used aggressive money printing to over-stimulate the Israeli economy, resulting in high inflation and a roaring housing bubble.

Investors want to see the Fed keep interest rates low for longer, but not for so long that it will be forced to act suddenly and unexpectedly to tackle inflation. All eyes and ears are on Yellen and how she views inflation and unemployment. In July she indicated that the rising inflation was merely “noise”; that monetary policy (rate hikes) should not be used to address asset bubbles; and that her main focus is now on ‘under-employment’, which is running at twice the rate of unemployment. In her Jackson Hole address at the end of August she hinted at possible rate rises early in 2015, rather than mid-year. But she also made it clear that she would be very careful and responsive to any adverse effects of rate rises on growth or employment.

It is the reverse in Australia. Here we have rising unemployment rates and rising inflation. In addition we still have very loose, and now politically chaotic, fiscal policy (big budget deficits and a hostile, volatile Senate). Inflation is already at the top end of the RBA’s target range but the RBA cannot raise interest rates to kill inflation and cool the housing market for fear of causing the dollar and unemployment to rise even further.

August saw the unemployment rate rise to 6.4%, up from a pre-GFC boom-time low of 3.9% in February 2008 at the peak of the commodities boom. Inflation is now up to 3%, the top of the RBA’s target range, and up from just 1.2% two years ago. Even ‘core’ inflation is now 2.9%. July also marked the start of the new Senate, with Palmer and other micro parties making fiscal policy and genuine economic reforms more challenging. This is dampening business confidence and investment and may necessitate the RBA providing monetary support for longer – ie keep interest rates low for longer.

As a result, the RBA, like the Fed in the US, will also probably act too late and too harshly with rate hikes. Indeed the RBA may even try another rate cut first to try to bring down the dollar. This would probably further inflame prices in the property and share markets, as well as accelerate consumer price inflation. That would mean it would need to come down even harder and harsher with rate hikes later on.


Ashley Owen is Joint CEO of Philo Capital Advisers and a director and adviser to the Third Link Growth Fund.


  •   29 August 2014
  • 1
  •      
  •   
1 Comments
Jerome Lander
September 05, 2014

Great article Ashley. For anyone left wondering why the markets are rising they need look no further than this. Excessively easy monetary policy has helped drive markets up and may well continue to do so for the time being, or at least until it becomes clearer that rates can rise as well as fall.

Investor portfolios are largely speaking completely dependent on this - sharemarkets, housing, infrastructure, property, bonds - you name it.

There are few real alternatives and they can't compete on price performance in this environment. Nonetheless prudent investors need to consider how much monetary policy risk they are willing to own, which is almost the same in this environment as saying how much risk they are willing to take. As markets continue to rise, and we get closer to the time to expectations of an interest rate rise, this risk will just become more and more acute.

This is a potentially very profitable but very risky environment for investors. Market timers will be nervously monitoring expectations as timing becomes more critical than ever. Those who reduce their risk exposures before the markets more broadly know interest rates rises are coming will be the ones who get to keep their (impressive) gains from their risky long only portfolios. Investors do not know yet when that time will be - it may be a while off yet or 2015 may indeed be an interesting year.


Leave a Comment:

RELATED ARTICLES

Brace, brace, brace: The real issue behind the banking turmoil

Is it all falling apart for central banks?

Shares rebound on hopes of war ending, but stalemate the likely outcome

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.